
Billboard Insider is continuing its series on out of home lenders. Today’s profile is based on an interview with Chris Stark of Stark Capital Solutions.
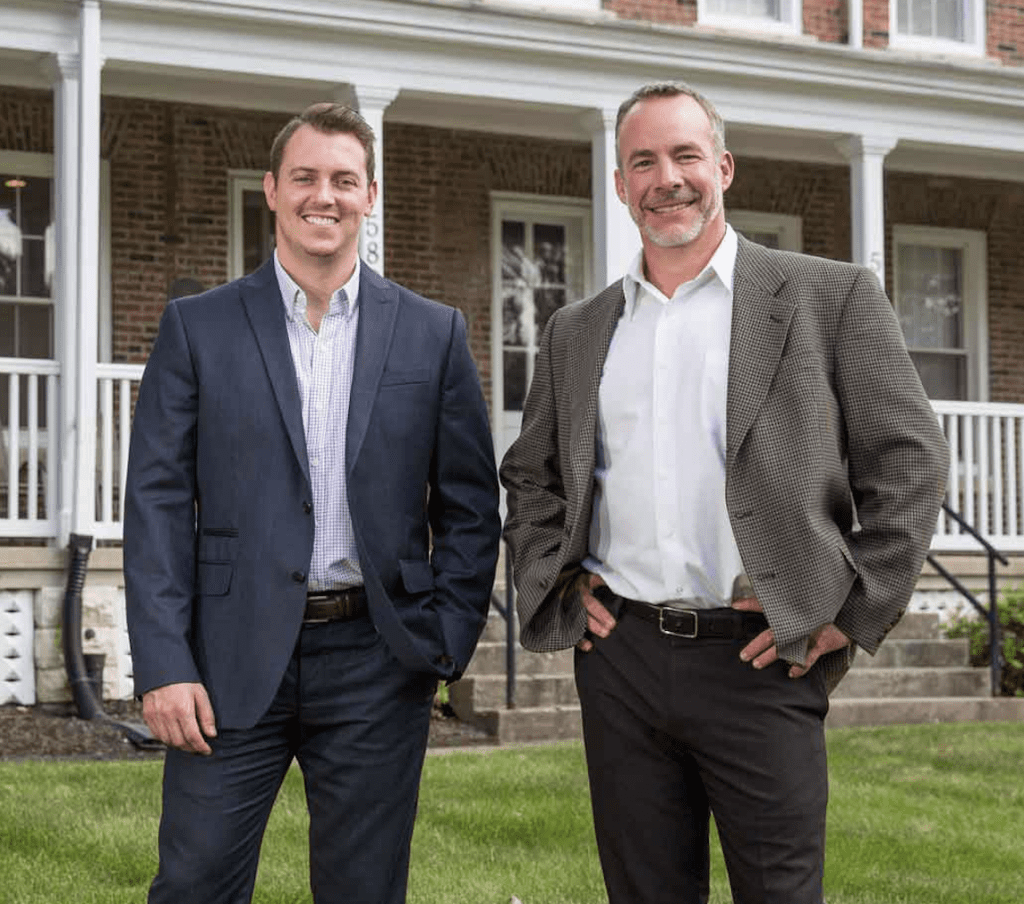
Lender: Stark Capital Solutions
Address: 5829 N Post Rd., Indianapolis, IN. 46216
Email: cstark@starkcapitalsolutions.com,
cberry@starkcapitalsolutions.com
Phone: 260-433-5833
Talk about your background in out of home:
I was first introduced to the out of home industry while in banking in the mid 1990’s. One of my largest clients was a private finance company (Midwest Bankers Group) that started lending to the industry. As their lender, I had to dig in and learn the industry. Like most lenders and investors new to the industry, I had a hard time believing the high market value of billboard assets in relationship to their cost to develop. It seemed almost too good to believe. Once I learned more about the substantial barriers to entry due to local and state regulation, along with the high cash flow margins and low annual maintenance cost, it clicked. I was hooked. I ended up leaving the bank and leading the out of home lending division for Midwest Bankers Group before going out on my own and forming Stark Capital in 2003.
What size loans are you seeking?
We have two basic loan programs for out of home operators:
- For borrowers that need development financing, or acquisition financing that requires reliance on projected cash flows, we seek loans between $250,0000 up to $17,000,000.
- For borrowers looking for a loan secured with assets that have existing cash flow, we seek loans between $500,000 and $99,000,000.
Most of our relationships fall between $1,000,000 to $20,000,000.
What is typical pricing (interest rate and loan fees)?
Loan fees and rates vary based on each project. Most loans have a 1-2% origination fee. Interest rates vary and change based on the global rate environment. With the current rate environment, our loans are priced between 7.75% – 10.75%.
Roadside billboards only or will you do place-placed, street furniture, transit and airports?
Most of our existing loan portfolio consists of roadside billboards or wallscapes. We have done financing for transit and street furniture as well. We have not funded place-based out of home yet. However, it is something we have been following and open to exploring.
What credit underwriting standards are important to you (e.g. leverage, covenants, loan term):
Most of our underwriting is focused on the specific billboard locations we will be financing vs. the net worth of the owner, or how many years of profitable operation the business entity has. Many of our borrowers have built and sold assets and companies over the years, so often our borrowing entity is newer with little historic performance. We spend a large portion of our underwriting process “proving out” the borrowers’ projections for new locations. We are fortunate to have decades of data from past transactions to help us determine if we need to inflate or deflate our borrowers’ projections for a given site.
Once we have verified the projections, the majority of our underwriting is centered around the cash flow available to cover the loan payment. We like to see the annual cash flow from a billboard being able to cover the annual loan payments with a cushion of 1.3x. In other words, we want a minimum of $1.30 in cash flow for every $1 in loan payment. If you keep a billboard loan to an amount that the billboard cash flow can comfortably service, you are almost always borrowing much less than the billboard is worth. This means the borrower always has equity in their assets, and as a lender we are always protected.
In most cases, the cash flow from a billboard location is sufficient for us to loan 100% of the cost to develop the location and still meet our cash flow cushion requirement. There are not many other industries where that is the case. A very simple “rule-of-thumb” is that you can usually count on being able to borrow ~5x the annual cash flow a billboard produces. In our experience, most quality new development locations can be built for 4x or less the annual cash flow they produce. What an amazing industry where if you build sites for around 4x their annual cash flow potential, you can finance 100% of the cost with no equity invested, and still have an asset that is worth 2-3 times the amount of your loan!
Tell us about an interesting lending transaction you’ve done recently.
We have a client with an impressive, multi-generation billboard company on the West Coast that has developed a unique and successful strategy for creating new billboard opportunities in municipalities that historically have not allowed billboards. In many cases the development projects take several years to acquire distressed property in the municipality, get the property rezoned, negotiate development agreements with the municipality that both addresses cleaning up the distressed property and provides needed non-tax income to the city.
This client utilizes its existing billboard assets to fund these long-term development projects. The existing assets being pledged generate significant cash flow and provide strong collateral support for our loans. Our client then uses our money vs. their own capital to fund the costs of the development project. Once the new development project is completed and generating cash flow, it is available to serve as collateral for the next development project. This creates a repeatable financing strategy that allows the client to creatively continue growing its portfolio while preserving its own capital. We recently closed on another
To receive a free morning newsletter with each day’s Billboard insider articles email info@billboardinsider.com with the word “Subscribe” in the title. Our newsletter is free and we don’t sell our subscriber list.
Paid Advertisement